Open (Investable) Crypto (Asset) Pricing
Investable cryptocurrency risk factors — and an honest map of how much your specification choices matter
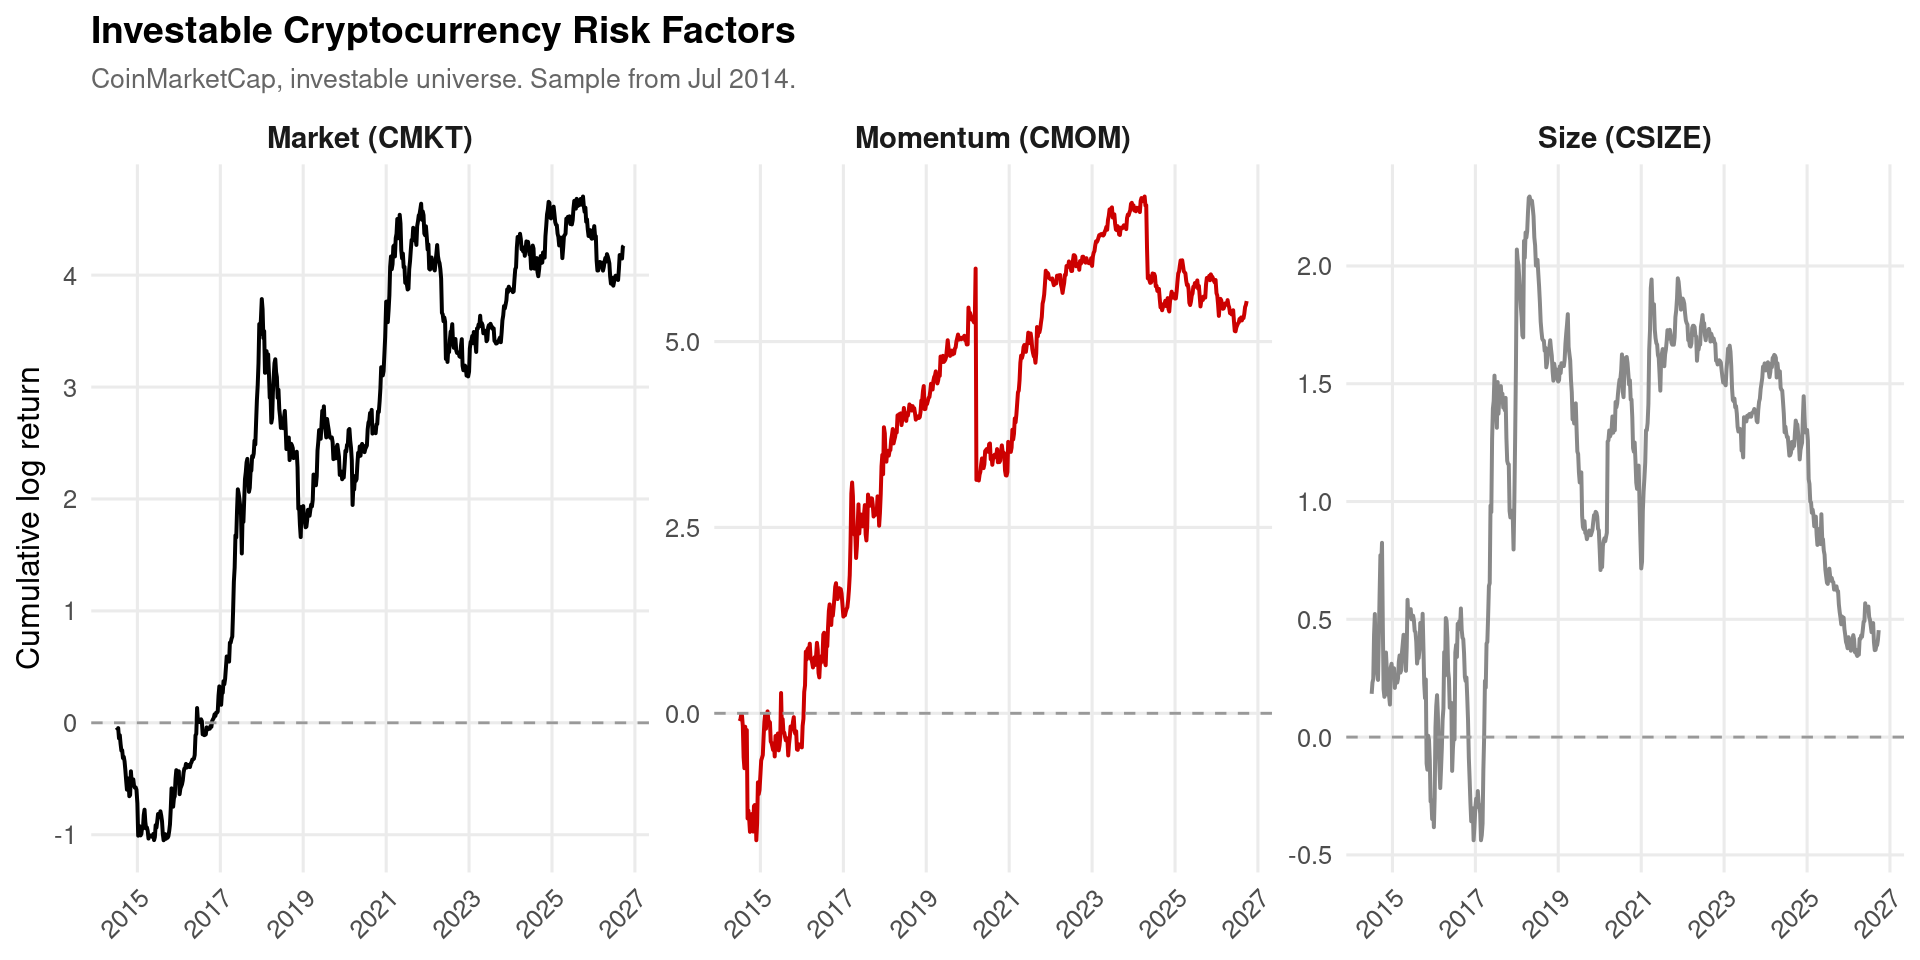
With the institutionalization of cryptocurrency markets, the question of how to price crypto assets has become central. Following this, the seminal paper by Liu et al. (2022) introduced one of the first factor models that prices the cross-section of crypto returns. In their model they propose three significant risk factors: market (CMKT), size (CSMB), and momentum (CMOM). Open Crypto Pricing builds on this work by providing a free and open-source replication of these risk factors together with the evidence on how robust they actually are.
The main finding of our work is that the crypto size premium is an artifact of non-investable microcaps. Once breakpoints are computed on the investable universe, the size premium vanishes. Only the short-term momentum risk premium can stay significant. On page Results the full analysis is presented, showing how the choice of universe, exclusions, breakpoints, and other choices can affect the pricing results.
Open Crypto Pricing provides three weekly factor series: CMKT, CSIZE, and CMOM.
Coverage: 2013-04-30 to 2026-09-24 (698 weeks) · Updated: 2026-09-28
Each factor is available in both investable and full-universe versions. The full specification multiverse includes exclusions, calendar choices, weighting schemes, breakpoints, and momentum horizons. All data is survivorship-bias-free with a transparent, reproducible construction.
Use the factors in R
The factors can be downloaded as CSV or Parquet files from the Download Data page.
The following example shows how to read the CoinGecko investable factors using R:
# CoinGecko & CoinMarketCap data via the crypto2 package
# install.packages("crypto2")
library(crypto2)

# Or pull the ready-made factor series directly:
url <- "https://opencryptopricing.com/data/factors_cg_investable.csv"
factors <- read.csv(url)   # week_start, CMKT, CSIZE, CMOM
Data sources
Cryptocurrency data is retrieved from both CoinMarketCap and CoinGecko using the crypto2 R package (CRAN) by Sebastian Stoeckl. This package provides the survivorship-bias-free (delisted/inactive coins retained) cryptocurrency cross-section for both data sources (CoinMarketCap and CoinGecko). We treat the choice of data source as one of the specification axes (see Results).
Citation
If you use these data, please cite Stoeckl & Pukrop (2026) and Liu et al. (2022).
@article{liu2022common,
  author  = {Liu, Yukun and Tsyvinski, Aleh and Wu, Xi},
  title   = {Common Risk Factors in Cryptocurrency},
  journal = {The Journal of Finance},
  volume  = {77},
  number  = {2},
  pages   = {1133--1177},
  year    = {2022},
  doi     = {10.1111/jofi.13119}
}


@misc{stoeckl2026opencrypto,
  author      = {Stoeckl, Sebastian and Pukrop, Moritz},
  title       = {Open Crypto Pricing},
  year        = {2026},
  institution = {University of Liechtenstein},
  url         = {https://huggingface.co/datasets/sstoeckl/opencryptoassetpricing}
}
References
Liu, Y., Tsyvinski, A., & Wu, X. (2022). Common risk factors in cryptocurrency. The Journal of Finance, 77(2), 1133–1177. https://doi.org/10.1111/jofi.13119
Stoeckl, S., & Pukrop, M. (2026). Open crypto pricing. University of Liechtenstein. https://huggingface.co/datasets/sstoeckl/opencryptoassetpricing