| Breakpoints | Weights | Designs | Mean Sharpe | Significantly positive | Significantly negative |
|---|---|---|---|---|---|
| All coins | Value | 27648 | -0.03 | 22% | 42% |
| Top 100 | Value | 27648 | -0.92 | 0% | 79% |
| ≥ $100M | Value | 27648 | -1.04 | 0% | 87% |
| All coins | Capped value | 27648 | 0.56 | 34% | 13% |
| Top 100 | Capped value | 27648 | -0.76 | 0% | 58% |
| ≥ $100M | Capped value | 27648 | -0.74 | 0% | 52% |
| All coins | Equal | 27648 | 0.92 | 39% | 9% |
| Top 100 | Equal | 27648 | -0.27 | 14% | 35% |
| ≥ $100M | Equal | 27648 | -0.22 | 16% | 33% |
Results
How much do specification choices matter for crypto factors?
Every published crypto factor rests on many small choices: the data source, filters, weighting, the number of portfolios, the week, and where breakpoints come from. We built the factors under every combination of the ten design choices of Fieberg et al. (2024), using two of their four data sources (CoinGecko and CoinMarketCap). We added three breakpoint universes and eight week calendars, for 248,832 designs in total. This page shows how much the answers depend on those choices. Unless noted, the numbers are annualised Sharpe ratios from 2018 onward. The Standard explains which design we recommend.
Momentum lives in value-weighted, investable portfolios
| Weights | Lag (days) | Designs | Mean Sharpe | Significantly positive | Significantly negative |
|---|---|---|---|---|---|
| Value | 0 | 41472 | 1.09 | 85% | 0% |
| Value | 1 | 41472 | 1.10 | 87% | 0% |
| Capped value | 0 | 41472 | 0.03 | 27% | 21% |
| Capped value | 1 | 41472 | 0.62 | 49% | 2% |
| Equal | 0 | 41472 | -2.36 | 2% | 64% |
| Equal | 1 | 41472 | -0.37 | 16% | 31% |
Momentum is robust in value-weighted designs and weak or negative elsewhere. For CMOM (winners minus losers, two-week momentum), 2018 onward, value-weighted momentum is strong and stable: it has the highest mean Sharpe of any weighting scheme, the large majority of designs are significantly positive, and almost none are significantly negative. The one-day implementation lag barely changes it, so value-weighted momentum here is not a lag artefact.
Capped-value weighting is weaker and more lag-sensitive: its mean Sharpe is close to zero at lag 0 and improves markedly at lag 1. Equal weighting is negative throughout, and its worst results are at lag 0. Equal-weighted “momentum” therefore looks less like momentum and more like microcap short-term reversal.
The one-day lag matters mainly where microcaps dominate the portfolio. It turns capped value positive and partially mitigates equal weighting, while leaving value-weighted momentum essentially unchanged. Taken together, the table supports a robust momentum premium in value-weighted, more investable designs, and little or no momentum in equal-weighted ones. Whether the equal-weighted loss is specifically microcap short-term reversal would need a direct decomposition, but the pattern is consistent with that interpretation.
Non-standard errors
Following Menkveld et al. (2024) and Fieberg et al. (2024), the non-standard error (NSE) is the standard deviation of a factor’s Sharpe ratio across designs. The standard error (SE) is the usual sampling uncertainty of one Sharpe ratio (Lo, 2002). Their ratio N/S tells how much more the result depends on the researcher’s choices than on the data.
| Period | Factor | Breakpoints | Designs | Mean Sharpe | NSE | SE | N/S |
|---|---|---|---|---|---|---|---|
| 2014-2021 | CMKT | All coins | 82944 | 1.20 | 0.46 | 0.37 | 1.26 |
| 2014-2021 | CMKT | Top 100 | 82944 | 1.20 | 0.46 | 0.37 | 1.26 |
| 2014-2021 | CMKT | ≥ $100M | 82944 | 1.20 | 0.46 | 0.37 | 1.26 |
| 2014-2021 | CSIZE | All coins | 82944 | 1.20 | 1.48 | 0.42 | 3.48 |
| 2014-2021 | CSIZE | Top 100 | 82944 | 0.50 | 0.85 | 0.42 | 2.03 |
| 2014-2021 | CSIZE | ≥ $100M | 82944 | 0.26 | 0.81 | 0.57 | 1.41 |
| 2014-2021 | CMOM | All coins | 82944 | -0.05 | 1.64 | 0.42 | 3.88 |
| 2014-2021 | CMOM | Top 100 | 82944 | 0.12 | 1.42 | 0.42 | 3.37 |
| 2014-2021 | CMOM | ≥ $100M | 82944 | 0.20 | 1.51 | 0.45 | 3.33 |
| 2018+ | CMKT | All coins | 82944 | 0.16 | 0.30 | 0.34 | 0.88 |
| 2018+ | CMKT | Top 100 | 82944 | 0.16 | 0.30 | 0.34 | 0.88 |
| 2018+ | CMKT | ≥ $100M | 82944 | 0.16 | 0.30 | 0.34 | 0.88 |
| 2018+ | CSIZE | All coins | 82944 | 0.48 | 1.56 | 0.34 | 4.52 |
| 2018+ | CSIZE | Top 100 | 82944 | -0.65 | 0.61 | 0.34 | 1.78 |
| 2018+ | CSIZE | ≥ $100M | 82944 | -0.67 | 0.68 | 0.36 | 1.86 |
| 2018+ | CMOM | All coins | 82944 | -0.08 | 1.88 | 0.35 | 5.45 |
| 2018+ | CMOM | Top 100 | 82944 | 0.05 | 1.62 | 0.34 | 4.72 |
| 2018+ | CMOM | ≥ $100M | 82944 | 0.08 | 1.64 | 0.34 | 4.77 |
For size and momentum, the design choices matter several times more than sampling noise. Investable breakpoints cut the non-standard error of the size factor by more than half.
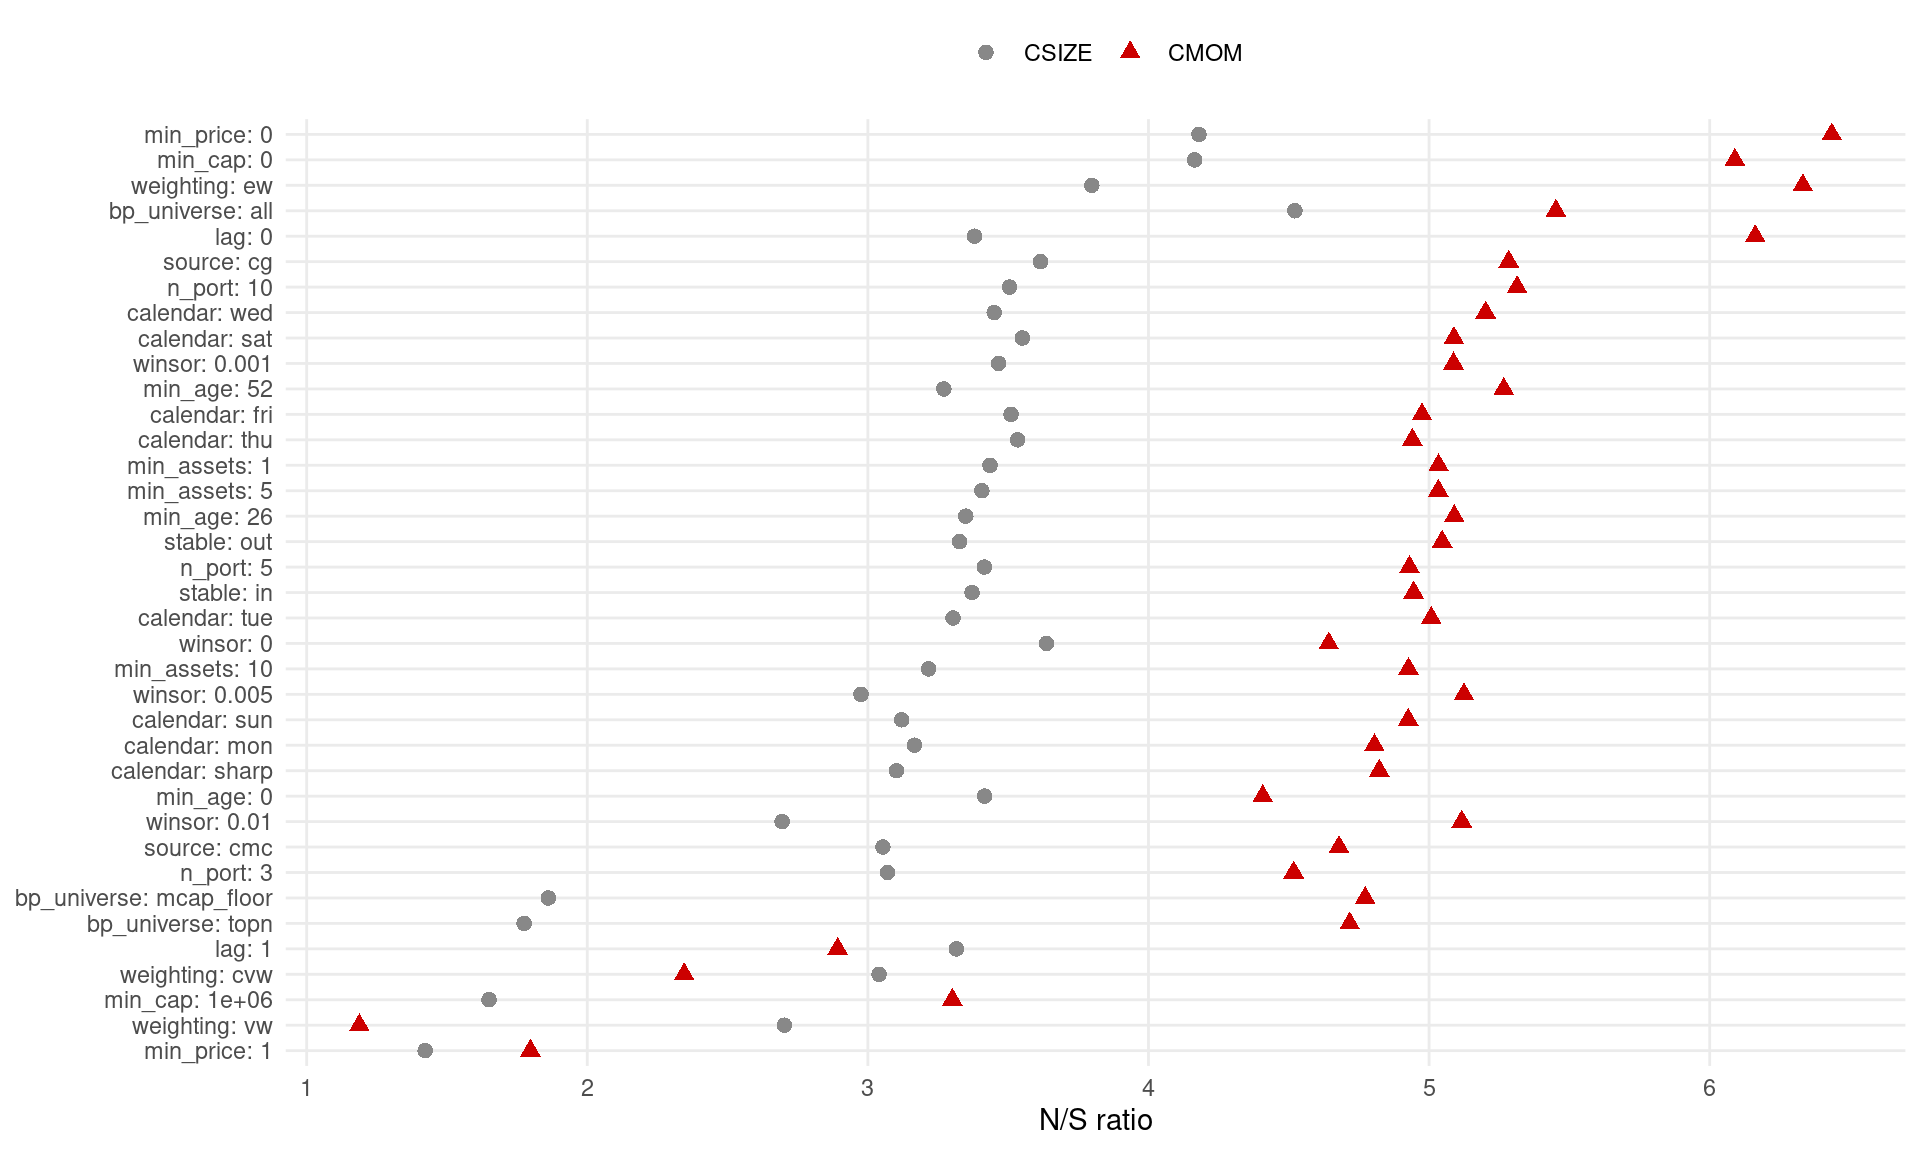
The effects of individual choices match those in Fieberg et al. (2024). Value weights, a $1M floor, a $1 minimum price and terciles reduce the dispersion; stablecoins make no difference. For momentum, value weights (N/S 1.2 instead of 6.3 with equal weights) and a one-day lag (2.9 instead of 6.2) matter most. Of the two choices that they do not vary, where the breakpoints come from matters as much as any of theirs for size (N/S 4.5 with all-coin breakpoints, 1.9 with breakpoints from coins ≥ $100M). Which day the week ends shifts individual weekly numbers, but changes the overall dispersion only modestly.
Where the standard sits
| Factor | Source | Weeks | Sharpe | t | Percentile, all designs | Percentile, investable VW designs |
|---|---|---|---|---|---|---|
| CMKT | CMC | 458 | 0.41 | 1.21 | 77% | 47% |
| CMKT | CG | 458 | 0.41 | 1.22 | 77% | 48% |
| CSIZE | CMC | 458 | -0.68 | -2.02 | 47% | 90% |
| CSIZE | CG | 458 | -0.83 | -2.45 | 36% | 76% |
| CMOM | CMC | 458 | 1.41 | 4.19 | 92% | 77% |
| CMOM | CG | 458 | 1.36 | 4.04 | 90% | 71% |
We did not choose the standard for its Sharpe ratios; see The Standard for the criteria. Its momentum factor is nonetheless among the strongest designs. Its size factor is negative, like that of most investable designs.
References
Fieberg, C., Günther, S., Poddig, T., & Zaremba, A. (2024). Non-standard errors in the cryptocurrency world. International Review of Financial Analysis, 92, 103106.
Lo, A. W. (2002). The statistics of Sharpe ratios. Financial Analysts Journal, 58(4), 36–52.
Menkveld, A. J. et al. (2024). Nonstandard errors. The Journal of Finance, 79(3), 2339–2390.